VVerdoos
Log in
JA

James

@jamesanderson

3 Posts0 Followers0 Following
JA
James@jamesanderson· September 5 at 9:08 AM

Nutraceuticals Market Size, Share & Trends 2026–2035

Market Overview According to Dimension Market Research, the Global Nutraceuticals Market size is estimated at USD 591.4 billion in 2026 and is projected to reach USD 1,141.6 billion by 2035, exhibiting a CAGR of 7.6% during the forecast period, driven by the rising use of better data tools in personalized nutrition, automated quality checks in manufacturing, and connected health management systems. The Global Nutraceuticals Market is expanding because of increasing use of smart software in detecting and analyzing consumer health patterns and ingredient effectiveness; increasing approvals which reduce the chance of rule-breaking during production and speed up the review process for new ingredients; and more funding in automating the use of nutrition-related health data. Some other reasons for expansion in this market are new technologies in real-time quality assurance, health risk prediction through body markers, automated supply chain handling, and high-volume digital platforms along with better data sharing rules. The digital shift in health and wellness companies has been helpful in speeding up product development and making nutraceutical management easier. This includes wellness tracking research. In addition, government plans focusing on preventing illness and the bio-economy have ensured steady research in functional foods and dietary supplements. Definition and Market Significance Nutraceuticals are products made from food sources that provide extra health benefits beyond basic nutrition, including helping to prevent and manage illness. They include dietary supplements, functional foods, and functional drinks. Nutraceuticals use modern systems such as online quality checks, formulation management software, and remote nutrition advice to manage, verify, and track health events and results. The importance of nutraceuticals lies in their ability to bridge the gap between food and medicine, offering consumers a proactive approach to health management. They support immunity, digestive health, cognitive function, and long-term illness management while reducing the burden on healthcare systems. Nutraceuticals also support broader preventive health initiatives by enabling personalized nutrition, improving health outcomes, and promoting wellness across diverse populations through accessible and science-backed products. Request a Complimentary PDF Sample https://dimensionmarketresearch.com/request-sample/nutraceuticals-market/ Market Drivers A major factor driving the Nutraceuticals Market is the fast growth in digital quality processing and data sharing. The market is growing with the rise of digital tools to check and process formulations, better management of health data, and closer connection of electronic health records and nutraceutical systems. Nutrition management platforms provide real-time data that allows monitoring of the product workflow, helping to spot differences early, and checking rules much faster. This has improved efficiency in operations and reduced human mistakes as well as administrative costs. The growing focus on rule-following and standardization in nutraceuticals is another key driver supporting market expansion. There is increasing emphasis on openness, ingredient accuracy, and rule-following within the nutraceutical system. Rules and frameworks such as the EU Health Strategy and nutrition modernization efforts in key markets are encouraging better data handling practices and more structured production processes. These advances are supporting the need for systems that can offer steady monitoring of formulations and standardized reporting. The rise in preventive healthcare awareness and government investments in national preventive health infrastructure are also contributing to market growth, as consumers increasingly seek products that support long-term wellness and disease prevention. Market Trends The growth of predictive risk modeling in nutraceuticals is emerging as an important trend. Nutraceutical platforms are gradually adding data-driven technology to find risk trends and improve accuracy in product development. These systems allow manufacturers to study their customers' buying behavior better, simplify the management of their product lines, and improve their overall performance. This move is slowly turning the industry more proactive and data-driven in nutrition management. Another significant trend is the growing use of internet-based formulation and quality management systems. The use of internet-based systems is currently becoming a basic part of today's nutraceutical operations. These systems allow real-time quality checks, centralized product administration, and better network coordination among health providers. Internet-based platforms are improving the efficiency and responsiveness of nutraceutical manufacturers that operate in different regions by removing the need to rely on physical infrastructure and allowing operations to grow more easily. The integration of artificial intelligence in formulation forecasting, quality trend detection, and ingredient sourcing analysis is also transforming the market, enabling faster quality checks, reduced operational workload, and improved product development accuracy. Market Restraints Despite its strong growth potential, the nutraceuticals market faces certain limitations. High costs of system setup and getting started pose significant challenges. The rollout of nutraceutical formulation platforms remains costly, requiring significant investment in system integration, testing, and alignment with health workflows. In addition, following data privacy rules such as GDPR and other regional laws adds to setup complexity. These factors increase upfront costs and can limit adoption, especially among smaller manufacturers and new companies entering the market. Limited standardization across health and nutraceutical systems is another significant restraint. There is still fragmentation in the market in terms of data formats and quality handling procedures. Although some areas have put in place organized nutrition management systems, many manufacturers continue to work with both digital and manual systems. Lack of standard rules limits the ability to share data between health providers and nutraceutical companies and results in inefficiencies in product development and system integration. In addition, the complexity of regulatory compliance across different regions and the need for continuous innovation to meet evolving consumer expectations create ongoing challenges for market participants. Market Opportunities The expansion of nutraceutical markets in developing economies presents a significant growth opportunity. Newly developing economies such as Brazil, Indonesia, Nigeria, the UAE, and Vietnam are slowly building their healthcare and nutraceutical systems. These regions have long-term growth possibilities, with more people adopting preventive health, and with more people becoming aware of functional foods and slowly digitizing nutrition care. These markets have few older production systems and can be used with new, technology-driven nutraceutical systems that can grow over time. The rising demand for internet-based nutraceutical systems is another promising opportunity. The move to remote nutrition care, spread-out health networks, and real-time quality checks is creating the adoption of internet-based nutraceutical systems. These systems allow centralized data access, better coordination between health providers and manufacturers, and faster product management. Internet-based setup is increasingly becoming a trend among modern nutraceutical providers as operational efficiency becomes one of the competitive factors. Furthermore, the growing focus on personalized nutrition and condition-specific product development is expected to open new opportunities for the nutraceuticals industry, enabling manufacturers to tailor products to individual health needs and preferences. Segmentation The Nutraceuticals Market is categorized based on ingredient, product, application, form, and distribution channel. By ingredient, the vitamins segment is likely to continue dominating the market in 2026, with 31.5% of the global nutraceuticals market share. This is due to its key role in covering immunity support, energy production, and long-term illness management, and its usefulness in various consumer settings where complete nutrition protection is needed. By product, the dietary supplements segment is expected to account for 58.7% share in 2026, due to higher consumer awareness, condition-specific health needs, and greater willingness to buy compared to other product types. The segment is also driven by growing adoption of complete vitamin and mineral plans, and combined formulation options. By application, the immunity support segment is expected to dominate with around 27.4% market share in 2026, driven by greater consumer focus on preventive health, faster product adoption, and broader store access compared to other applications. By form, the tablets segment is the largest in 2026, accounting for 27.5% share, driven by ease of swallowing, exact dosing, and longer shelf life. Gummies are the fastest-growing area, where consumers prefer chewable, good-tasting alternatives to traditional pills. By distribution channel, the online retail segment is the largest in 2026, accounting for 35.6% share, driven by digital adoption, subscription plans, and the ease of buying products via websites and mobile apps. Regional Analysis North America is projected to take the lead in the global nutraceuticals market (by value), covering a market share of about 35.2% in the year 2026. The region's dominance is driven by strong preventive healthcare spending funded by private and public sources, higher average product prices compared to other regions, a mature digital supply chain for advanced data sharing, and the presence of major nutraceutical manufacturers and health networks. The US market is estimated to grow to USD 175.1 billion in 2026 with a CAGR of 7.1%. Europe holds a substantial share of the nutraceuticals market, estimated at USD 159.7 billion in 2026, with a CAGR of 6.4%. The market is well-established, shaped by EU-wide policies such as the EU Health Strategy, the European Horizon Europe research program, and national policies to support digital health, with countries making nutraceutical processes more flexible to align producer and consumer demands. Asia Pacific is the fastest-growing region, supported by strong digital health infrastructure goals in China, India, and Japan, increasing preventive health awareness efforts, rising investments in local nutraceutical capabilities, and growing adoption of automated quality analysis systems. Japan's market is projected to be valued at USD 18.8 billion in 2026, progressing at a CAGR of 7.3%. Latin America and the Middle East & Africa are gradually adopting nutraceutical products as health awareness increases and digital infrastructure improves, with Brazil, Mexico, the UAE, and Saudi Arabia emerging as key markets. Competitive Landscape The nutraceuticals market is highly competitive, with new ideas and strategic partnerships shaping the competitive environment. To gain an advantage, companies and manufacturers are focused on developing better digital platforms (such as smart formulation engines, automated quality systems, and mobile apps for product management), smart data analysis, and digital platform-based quality monitoring. There are high barriers to entering the market due to the large amount of money needed for regulatory approval, specialized nutrition knowledge, and the need for mature software systems and rule-following. Prominent players include Nestlé S.A., Abbott Laboratories, Amway Corporation, Herbalife Nutrition Ltd., Archer Daniels Midland Company, Danone S.A., Glanbia plc, Bayer AG, DSM-Firmenich, BASF SE, PepsiCo Inc., General Mills Inc., Nature's Bounty (The Bountiful Company), GNC Holdings LLC, Ajinomoto Co., Inc., Cargill, Incorporated, Kerry Group plc, International Flavors & Fragrances Inc., Ingredion Incorporated, and Blackmores Limited. Recent developments include Otsuka Holdings' launch of new functional nutrition products (February 2026), Kerry Group's Plenibiotic postbiotic solutions (February 2026), Nestlé's expansion of its Materna nutrition range (December 2025), and Yakult Honsha's global production capacity expansion (March 2025). Technological Advancements Rapid advancements in AI-powered formulation forecasting, real-time quality analysis, and cloud-based product management are transforming the nutraceuticals market. AI enables faster quality checks, improved risk assessment, and more accurate product planning, while cloud-based platforms allow centralized data access and better coordination between health providers and manufacturers. The integration of predictive health risk tracking and automated supply chain handling is also playing a significant role, enabling manufacturers to predict product demand, find possible processing delays, and monitor supplier network performance more effectively. Consumer Adoption Patterns Consumers are increasingly adopting nutraceutical products for immunity support, digestive health, energy and performance, weight management, and cognitive health. The growing availability of online retail channels, subscription plans, and personalized nutrition options is making these products more accessible to a broader consumer base. Regulatory Environment Regulatory frameworks such as the Dietary Supplement Health and Education Act in the United States, the EU Health Strategy, and various national nutrition policies influence the nutraceuticals market. Compliance with data privacy regulations, ingredient safety standards, and labeling requirements is essential for market participants. Market Challenges The nutraceuticals market faces challenges related to high system setup costs, limited standardization across health systems, regulatory complexity, and the need for continuous innovation. Additionally, ensuring ingredient quality and efficacy while meeting evolving consumer expectations remains an ongoing challenge for manufacturers. Future Outlook The future of the Nutraceuticals Market remains highly promising as consumers increasingly prioritize preventive health and personalized nutrition. Growing adoption of digital quality processing, AI-powered formulation tools, and internet-based management systems, along with expanding markets in developing economies, are expected to drive strong market growth during the forecast period, with the market projected to reach USD 1,141.6 billion by 2035. FAQs What is the expected size of the Nutraceuticals Market in 2026? The market is expected to reach USD 591.4 billion in 2026. What is the projected market value by 2035? The market is forecast to reach USD 1,141.6 billion by 2035. What is the CAGR of the Nutraceuticals Market? The market is expected to grow at a CAGR of 7.6% during 2026–2035. Which ingredient segment dominates the market? The vitamins segment is expected to lead with 31.5% share in 2026. Which region leads the global nutraceuticals market? North America is projected to take the lead with a 35.2% share in 2026. Summary of Key Insights The global Nutraceuticals Market is expected to grow from USD 591.4 billion in 2026 to USD 1,141.6 billion by 2035, recording a CAGR of 7.6% during the forecast period. Vitamins lead the ingredient segment with 31.5% share, while dietary supplements dominate products with 58.7% share. Immunity support leads applications with 27.4% share, tablets lead forms with 27.5% share, and online retail leads distribution channels with 35.6% share. North America holds the largest regional share with 35.2% of global revenue in 2026, while Asia Pacific is projected as the fastest-growing region. The US market is estimated to reach USD 175.1 billion in 2026 at a CAGR of 7.1%. Purchase the Full Report https://dimensionmarketresearch.com/checkout/nutraceuticals-market/
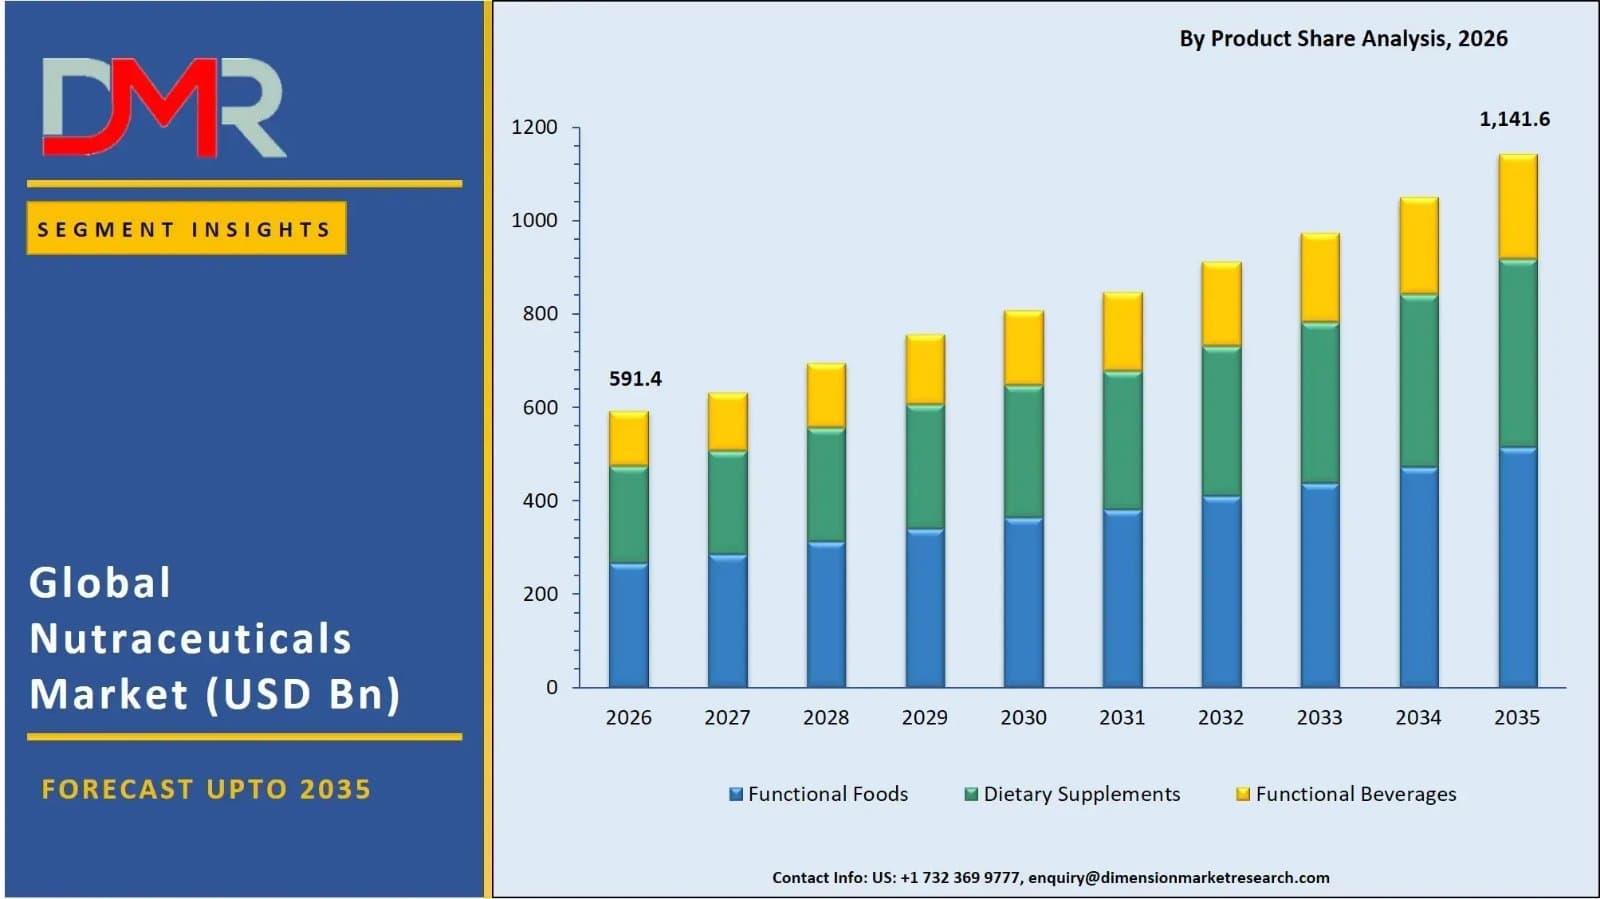
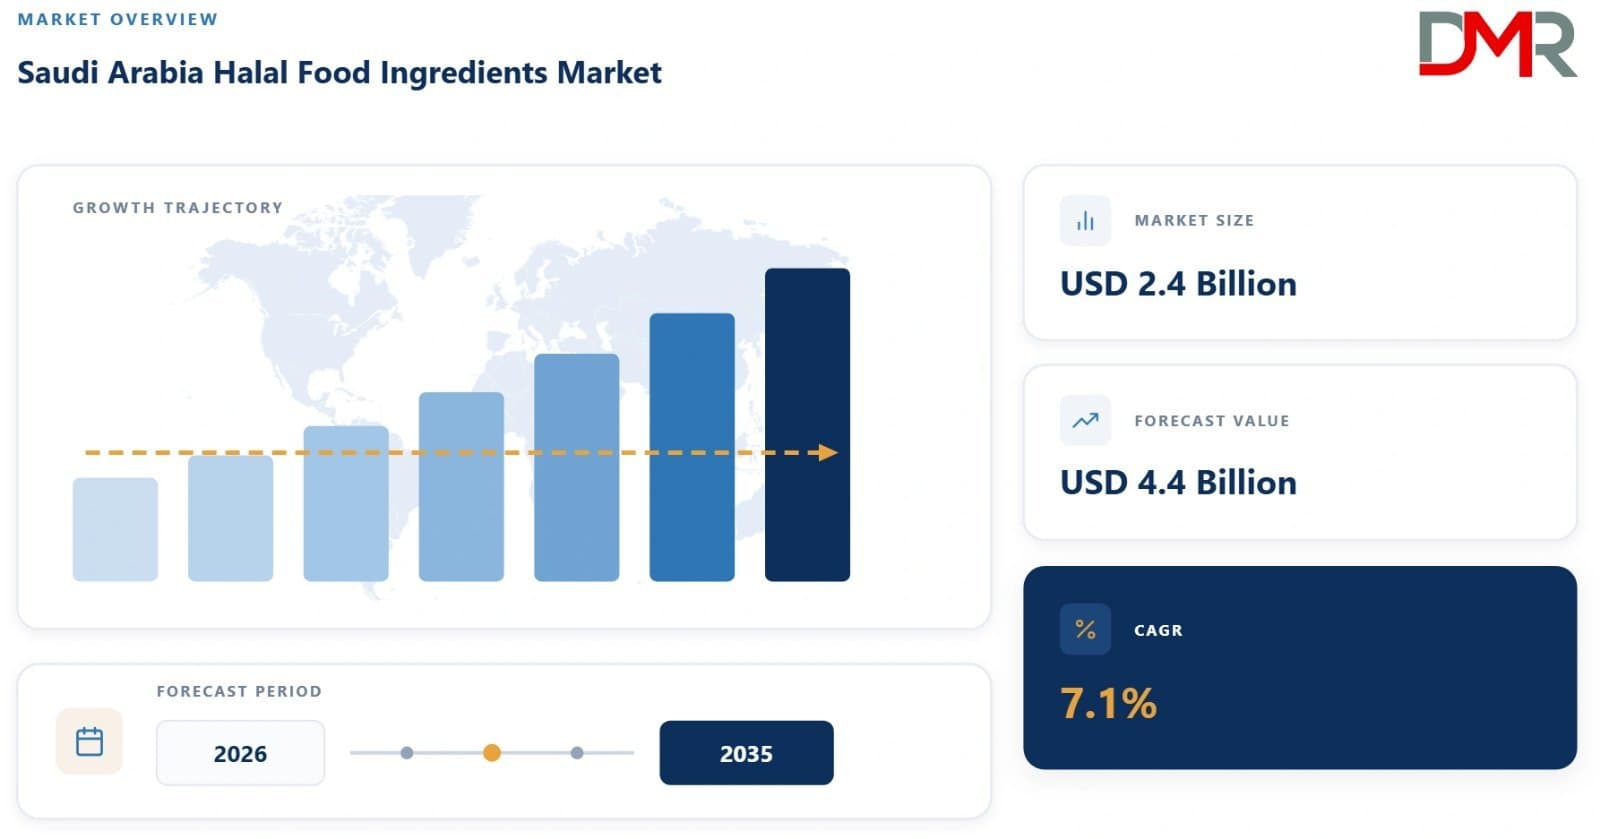
Photo shared by James: Market Overview

According to Dimension Market Research, the Global Nutraceuticals Market size is
JA
James@jamesanderson· August 20 at 7:33 AM

Saudi Arabia Halal Food Ingredients Market Size 2026-2035

Market Overview According to Dimension Market Research, the Saudi Arabia Halal Food Ingredients Market size is estimated to reach USD 2.4 billion in 2026 and is further anticipated to reach USD 4.4 billion by 2035, at a CAGR of 7.1%. The market is experiencing steady growth due to localization of processed food manufacturing, rising demand for halal traceability and compliance, and expanding processed food and convenience food sectors across the Kingdom. Halal food ingredients are formulation inputs, processing aids and functional materials whose source, manufacturing route, handling and documentation meet applicable halal requirements for food production. The category includes certified proteins, amino acids, flavors, colors, emulsifiers, stabilizers, enzymes, vitamins, minerals, starches, sweeteners and related specialty ingredients. The sizing covers demand generated inside Saudi Arabia rather than worldwide revenue of Saudi-headquartered companies. It captures ingredients purchased by food and beverage manufacturers, meat and poultry processors, bakeries, confectionery producers, dairy companies, beverage plants, convenience food manufacturers and foodservice-oriented processors. Final packaged halal foods, certification services, pharmaceuticals, cosmetics and non-food applications are outside the market boundary. Saudi demand is structurally different from generic ingredient consumption because manufacturers must consider raw-material origin, processing media, cross-contamination controls, documentation and approved certification routes. Animal-derived gelatin, enzymes, emulsifiers, flavor carriers and certain processing aids can require particularly detailed verification, making traceability and technical documentation commercially important alongside price, functionality and supply reliability. Growth is also tied to localization of food manufacturing, expansion of processed foods and rising demand for nutrition, convenience and clean-label formulations. Manufacturers are shifting from simple commodity procurement toward ingredients that solve texture, shelf life, taste, fortification and process-efficiency problems. Definition and Market Significance Halal food ingredients are formulation inputs, processing aids, and functional materials whose source, manufacturing route, handling, and documentation comply with Islamic dietary requirements for food production. This category encompasses certified proteins, amino acids, flavors, colors, emulsifiers, stabilizers, enzymes, vitamins, minerals, starches, sweeteners, and related specialty ingredients. The importance of halal food ingredients lies in their critical role in enabling food manufacturers to produce halal-certified finished products while maintaining functionality, shelf life, and sensory quality. These ingredients ensure compliance with religious requirements, build consumer trust, and facilitate market access in the Kingdom and across the broader Islamic world. Halal food ingredients also support broader food security and localization goals under Vision 2030, enabling domestic manufacturers to reduce import dependence, increase local value addition, and meet growing demand for processed and convenience foods across Saudi Arabia. Request a Complimentary PDF Sample https://dimensionmarketresearch.com/request-sample/saudi-arabia-halal-food-ingredients-market/ Market Drivers A major factor driving the Saudi Arabia Halal Food Ingredients Market is the localization of processed food manufacturing. Direct sales are expected to account for approximately 46.5% of 2026 distribution revenue because larger processors increasingly source technical ingredients through direct supplier relationships. New and expanded domestic food plants create recurring demand for flavors, proteins, enzymes, stabilizers and fortification systems rather than only finished imported foods. Local production also requires ingredient adaptation to Saudi taste profiles, climate, shelf-life requirements and processing conditions, raising demand for both imported specialty ingredients and locally stocked formulation systems. Halal traceability and compliance requirements are another key driver supporting market expansion. Animal-derived ingredients are projected to represent around 28.7% of 2026 source demand, making origin verification commercially significant for gelatin, collagen, selected enzymes and emulsifier feedstocks. Manufacturers must establish that raw materials, processing aids and handling practices align with halal requirements, particularly where supply chains cross several countries. This favors suppliers with recognized certification, segregated handling and complete documentation, reducing the risk of rejected materials, reformulation delays and market-access problems. The expansion of processed foods and convenience food manufacturing across the Kingdom is also contributing to market growth, as manufacturers require integrated ingredient systems that combine functionality, compliance and technical support. Market Trends The shift toward plant and fermentation-derived inputs is emerging as an important trend. Plant-based sources are expected to hold approximately 41.2% of 2026 revenue because starches, fibers, plant proteins, gums, colors and botanical extracts fit a wide range of food applications with straightforward source narratives. Microbial and fermentation-derived ingredients are growing faster because they can replace certain animal-derived enzymes, cultures and functional compounds while offering consistency at industrial scale. Another significant trend is clean label with functional performance. Flavor and taste enhancement is projected to represent close to 24.8% of 2026 functional demand as manufacturers balance recognizable ingredient lists with strong sensory performance. Natural flavors, spice extracts, yeast-based taste systems and multifunctional ingredients are gaining interest where they can reduce dependence on several separate additives while maintaining shelf stability, texture and process tolerance. The integration of AI and digital tools for formulation assistance, certificate documentation and traceability is also transforming the market, enabling faster development cycles and improved compliance management. Market Restraints Despite its steady growth potential, the Saudi Arabia halal food ingredients market faces certain limitations. Import dependence for high-specification ingredients poses a significant challenge. Specialty distributors are expected to hold close to 38.2% of 2026 distribution revenue because many manufacturers depend on imported flavors, cultures, enzymes, hydrocolloids and micronutrient systems. Long lead times, freight volatility, minimum order quantities and supplier qualification requirements make inventory planning difficult, increasing working-capital requirements and encouraging manufacturers to hold safety stock. Certification and reformulation complexity is another significant restraint. Enzymes and processing aids are expected to account for roughly 13.6% of 2026 ingredient-type demand, but they can require detailed review because their production organisms, nutrient media, carriers or processing origins are not always obvious from the final ingredient name. A supplier change can trigger documentation review, plant-quality approval and sometimes reformulation work, raising the cost of switching suppliers and slowing adoption of novel ingredients. In addition, smaller buyers face the greatest constraint because they lack the scale to negotiate direct contracts or reserve production slots with major international ingredient suppliers. Market Opportunities Local production of halal specialty ingredients presents a significant growth opportunity. Enzymes and processing aids are forecast to expand at a CAGR of 9.6% from 2026-2035, creating an opportunity for local blending, application laboratories and eventually production of selected specialty inputs. Saudi manufacturers often import these materials in finished form, so domestic capability could shorten lead times and simplify technical support. Local production is most realistic first in blends, seasonings, premixes, stabilizer systems and application-specific solutions. Fortification and better-for-you formulations are another promising opportunity. Nutritional enhancement is forecast to grow at a CAGR of 9.0% from 2026-2035 as manufacturers add proteins, fibers, vitamins, minerals and lower-sugar systems to mainstream foods and beverages. Halal-compliant nutrient premixes and functional systems that remain stable during heat treatment are particularly attractive. Furthermore, the growing demand for fermentation-derived ingredients and the expansion of digital B2B channels for standardized, documented ingredients are expected to open new opportunities for the halal food ingredients industry. Segmentation The Saudi Arabia Halal Food Ingredients Market is categorized based on ingredient type, source, application, function, and distribution channel. By ingredient type, proteins and amino acids are projected to hold the largest share in 2026 at approximately 27.8%, supported by meat processing, dairy nutrition, sports-oriented foods and fortified products. Growth is concentrated in enzymes and processing aids, expanding at a CAGR of 9.6% from 2026-2035. By source, plant-based ingredients are expected to lead source demand in 2026 with around 41.2% of revenue. The steeper trajectory sits with microbial and fermentation-derived ingredients, forecast to grow at a CAGR of 10.1% from 2026-2035. By application, meat and poultry is projected to account for the largest share in 2026 at close to 29.6%, driven by Saudi Arabia's large consumption base and extensive use of seasonings, proteins, binders, antioxidants and texture systems. Growth is concentrated in convenience foods, forecast to expand at a CAGR of 9.2% from 2026-2035. By function, flavor and taste enhancement is expected to hold the largest functional share in 2026 at approximately 24.8%. Growth is stronger in nutritional enhancement, projected at a CAGR of 9.0% from 2026-2035. By distribution channel, direct sales are projected to represent the largest share in 2026 at around 46.5%. The fastest growth is expected in online and digital B2B channels, with a CAGR of 11.3% from 2026-2035. Regional Analysis Competition combines multinational ingredient producers with specialized distributors and Saudi trading companies. Large suppliers compete through halal-certified portfolios, technical formulation support, global sourcing and consistency across production sites. Local distributors differentiate through stock availability, Arabic and English documentation support, smaller order quantities and relationships with domestic processors. Market power varies by ingredient: commodity starches and sweeteners are price-sensitive, while flavors, cultures, enzymes, hydrocolloids and nutrient systems depend more heavily on application expertise and qualification history. Strategic advantage increasingly comes from combining recognized certification with local warehousing, fast sample delivery, regulatory support and application laboratories, allowing suppliers to reduce development time for Saudi manufacturers. Competitive Landscape Key participants include Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, dsm-firmenich, Givaudan SA, International Flavors & Fragrances Inc., Symrise AG, BASF SE, Corbion N.V., Palsgaard A/S, Roquette Frères, Lesaffre, Puratos Group, BENEO GmbH, Döhler GmbH, Sensient Technologies Corporation, Jungbunzlauer Suisse AG, Ajinomoto Co., Inc., Angel Yeast Co., Ltd., Kemin Industries, Inc., Glanbia plc, Darling Ingredients Inc., Griffith Foods, AAK AB, Sahaa Ingredients, Hendami Trading Company, Transarq Trading Company, Food & Nuts Company, FoodNation, Tala Al-Joud Holding Company, Mawasim Taibah Trading Est., MATERA Chem, Resource Food Company, Pan Gulf Foods Company Ltd., Al Babtain Food, Ahmad Abdulwahab Abed Trading Co. Ltd., Al Rasheed Trading, and Al Eid Est. Recent developments include the Saudi Food and Drug Authority's expanded cooperation with Indonesia's halal authority on digital certification (February 2026), a cooperation agreement with Thailand's Central Islamic Council (February 2026), JBS's expanded Jeddah production facility (January 2026), a cooperation agreement with Türkiye's Halal Accreditation Agency (November 2025), and Tanmiah Food Company and Griffith Foods' evaluation of a Saudi joint venture for local halal ingredient production (March 2025). Technological Advancements AI and generative AI are transforming the Saudi Arabia halal food ingredients market through certificate document screening, formulation assistance, demand forecasting, and process optimization. Machine learning can compare ingredient specifications, certificate histories, supplier performance and batch data to identify inconsistencies before material enters production. Generative AI can organize halal certificates, specifications, allergen statements and supplier declarations, while formulation tools can narrow candidate ingredient combinations before bench trials begin. Digital twins can also model process behavior for mixing, heating or stabilization when manufacturers scale a recipe from pilot to industrial production, reducing trial-and-error during scale-up. Consumer Adoption Patterns Food and beverage manufacturers, meat processors, bakeries, confectionery producers, dairy companies, and convenience food manufacturers are increasingly adopting halal-compliant ingredient systems that combine functionality, traceability, and technical support. The growing availability of local warehousing, application laboratories, and digital B2B channels is making these ingredients more accessible to manufacturers of all sizes. Regulatory Environment The Saudi Food and Drug Authority (SFDA) oversees halal certification and ingredient compliance in the Kingdom. International cooperation agreements with halal authorities in Indonesia, Thailand, Türkiye, and other countries support mutual recognition, digital certification, and QR-based verification, strengthening the infrastructure used to validate imported halal products and ingredient documentation. Market Challenges The Saudi Arabia halal food ingredients market faces challenges related to import dependence for high-specification ingredients, certification and reformulation complexity, and the cost of maintaining compliant, segregated supply chains. Additionally, the need for continuous technical support and the risk of supply chain disruptions due to global events can affect market stability. Future Outlook The future of the Saudi Arabia Halal Food Ingredients Market remains positive as food-manufacturing localization accelerates and demand for processed, convenience, and fortified foods grows across the Kingdom. Increasing adoption of fermentation-derived ingredients, clean-label systems, digital documentation, and local specialty ingredient production are expected to support steady market growth during the forecast period. FAQs What is the expected size of the Saudi Arabia Halal Food Ingredients Market in 2026? The market is expected to reach USD 2.4 billion in 2026. What is the projected market value by 2035? The market is forecast to reach USD 4.4 billion by 2035. What is the CAGR of the Saudi Arabia Halal Food Ingredients Market? The market is expected to grow at a CAGR of 7.1% during 2026–2035. Which ingredient type holds the largest share? Proteins and Amino Acids are expected to hold the leading 2026 share at approximately 27.8%. Which source category is growing fastest? Microbial and Fermentation-Derived ingredients are forecast to grow at a CAGR of 10.1% from 2026-2035. Summary of Key Insights The Saudi Arabia Halal Food Ingredients Market is expected to grow from USD 2.4 billion in 2026 to USD 4.4 billion by 2035, recording a CAGR of 7.1% during the forecast period. Proteins and Amino Acids lead the ingredient type segment with 27.8% share, while Plant-Based sources dominate with 41.2% share. Meat and Poultry leads applications with 29.6% share, and Flavor and Taste Enhancement leads functions with 24.8% share. Direct Sales lead distribution channels with 46.5% share, while Online and Digital B2B Channels are the fastest-growing segment. Microbial and Fermentation-Derived ingredients are the fastest-growing source category at a CAGR of 10.1%. Purchase the Full Report https://dimensionmarketresearch.com/checkout/saudi-arabia-halal-food-ingredients-market/

Photo shared by James: Market Overview

According to Dimension Market Research, the Saudi Arabia Halal Food Ingredients M
JA
James@jamesanderson· August 6 at 6:12 AM

Data Observability Market Size, Share & Trends 2025-2034

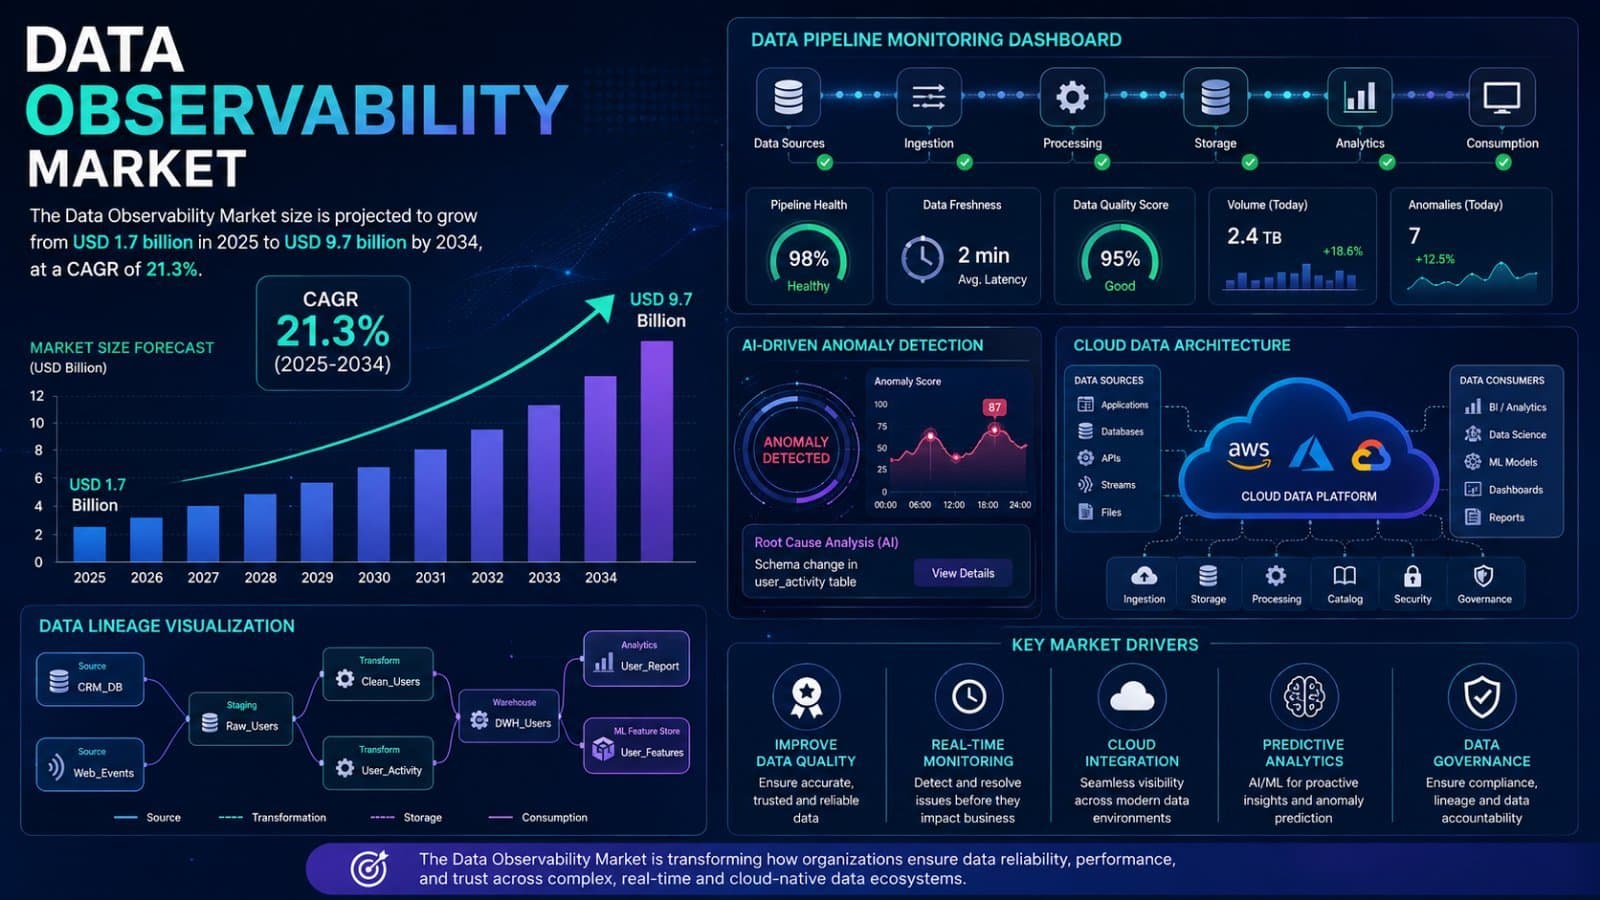
Market Overview According to Dimension Market Research, the Global Data Observability Market is projected to reach USD 1.7 billion in 2025 and surge to USD 9.7 billion by 2034, growing at a robust CAGR of 21.3%. This growth is driven by growing adoption of data reliability tools, real-time monitoring platforms, and AI-powered observability solutions across cloud-native and hybrid data ecosystems. Data observability refers to an organization's ability to fully understand the health and quality of its data systems. It involves continuous monitoring, tracking, and analysis of data flows, pipelines, and transformations across complex IT infrastructures. Leveraging advanced telemetry, metadata analysis, anomaly detection, and automated alerting, data observability ensures that data remains accurate, timely, and trustworthy across its lifecycle. It empowers data engineers, analysts, and IT operations teams to detect data outages, quality issues, schema changes, and lineage breakdowns in real time, thereby enabling proactive troubleshooting and maintaining data reliability in both batch and real-time environments. The global data observability market is witnessing significant growth driven by the rapid proliferation of data across cloud-native platforms, big data architectures, and AI-powered analytics ecosystems. As enterprises scale their digital transformation efforts, the complexity of data pipelines and the demand for trustworthy data have intensified, creating a strong need for comprehensive observability solutions. Businesses across sectors such as finance, healthcare, retail, and telecom are adopting data observability platforms to enhance data governance, reduce downtime, and ensure seamless data integration across heterogeneous systems. Definition and Market Significance Data observability is the practice of continuously monitoring, tracking, and analyzing the health, quality, and reliability of data as it flows through an organization's data pipelines, systems, and transformations. It leverages telemetry, metadata, anomaly detection, and automated alerting to provide end-to-end visibility into data infrastructure. The importance of data observability lies in its ability to proactively detect and resolve data issues—such as schema changes, pipeline failures, data drift, and quality degradation—before they impact downstream analytics, business intelligence, or AI applications. By providing real-time insights and root cause analysis, it enables organizations to maintain data trust and operational continuity. Data observability also supports broader data governance and compliance initiatives by ensuring data accuracy, traceability, and auditability across complex, distributed environments, making it a critical component of modern data-driven enterprises. Request a Complimentary PDF Sample https://dimensionmarketresearch.com/request-sample/data-observability-market/ Market Drivers A major factor driving the Data Observability Market is the rising complexity of data infrastructure across enterprises. The growing adoption of hybrid and multi-cloud environments, combined with microservices and distributed data architectures, is significantly increasing data pipeline complexity. This has created a strong need for comprehensive data observability platforms that offer real-time monitoring, automated anomaly detection, and end-to-end data lineage. The demand for reliable and trustworthy data in decision-making is another key driver supporting market expansion. Organizations across industries are increasingly relying on analytics, machine learning, and real-time dashboards for strategic decisions. As a result, the demand for high-quality, accurate, and timely data has surged, making data observability tools essential for maintaining data trust. Regulatory pressures around data privacy and compliance, integrated with the growing adoption of hybrid and multi-cloud environments, are further fueling market expansion, as organizations require robust observability solutions to ensure traceability, accuracy, and real-time alerting. Market Trends The integration of AI and machine learning in observability platforms is emerging as an important trend. AI-driven observability tools enable intelligent alerting, predictive analytics, and contextual root cause analysis, detecting anomalies in real time and adapting to changes in data patterns without manual intervention. Another significant trend is the shift toward unified data observability and governance platforms. Organizations are increasingly looking for holistic platforms that combine observability, data cataloging, lineage, and governance features within a single framework, enabling teams to manage data quality, compliance, and observability seamlessly. The growing adoption of DataOps and automation in analytics workflows is also transforming the market. As organizations embrace DataOps practices to streamline data pipelines, the need for automated data quality monitoring and observability becomes more pronounced, creating opportunities for scalable, AI-enabled solutions. Market Restraints Despite its strong growth potential, the data observability market faces certain limitations. High implementation costs and integration challenges can restrict adoption, especially for small and mid-sized enterprises. Integrating these tools with legacy data systems, BI platforms, and cloud infrastructure often requires customization, skilled resources, and extended implementation timelines. The lack of standardization and unified metrics in data observability is another significant restraint. The space is still evolving, with no universally accepted framework or set of metrics to define and measure data health, leading to confusion among end-users and inconsistent practices across organizations. In addition, the shortage of skilled professionals capable of implementing and managing observability platforms can slow adoption, particularly in organizations with limited technical expertise. Market Opportunities The growing adoption of DataOps and automation in analytics workflows presents a significant opportunity. As organizations embrace DataOps practices, the need for automated data quality monitoring and observability becomes more pronounced, offering vendors a chance to provide scalable, AI-enabled observability solutions that support automation, collaboration, and agility. The expanding role of observability in cloud migration and modernization projects is another promising opportunity. Many enterprises are moving from on-premise systems to cloud platforms like Snowflake, Databricks, and Google BigQuery, where observability plays a key role in tracking data movement, ensuring consistency, and reducing migration risks. Furthermore, the development of affordable, user-friendly, and SaaS-based observability solutions is opening new opportunities for small and medium-sized enterprises, enabling them to implement data observability tools despite budget and resource constraints. Segmentation The Data Observability Market is categorized based on component, deployment mode, data type, organization size, application, and industry vertical. By component, software components are expected to dominate with approximately 72.0% of the market share in 2025, driven by widespread adoption of standalone and integrated observability platforms that offer real-time monitoring, automated root cause analysis, anomaly detection, and data lineage tracking. By deployment mode, cloud-based deployment is projected to dominate with 66.0% of the market share in 2025, driven by the growing shift of enterprises toward cloud-native data infrastructure that requires scalable, flexible, and cost-effective observability solutions. By data type, structured data is expected to maintain a dominant position with 58.0% of the market share in 2025, largely due to its widespread use across enterprise applications, relational databases, and business intelligence platforms. By organization size, large enterprises are expected to dominate with 68.0% of the market share in 2025, driven by their complex data environments, larger IT budgets, and strong need for real-time data quality management. By application, data pipeline monitoring applications are expected to capture the largest share with 28.0% of the market value in 2025, primarily due to the growing complexity of modern data environments where data moves through multiple sources, transformation stages, and destinations. By industry vertical, hospitals and clinics are anticipated to dominate with 40.0% of the market share in 2025, driven by the healthcare sector's growing dependence on real-time data for patient care, diagnostics, and medical research. Regional Analysis North America is projected to lead the global data observability market in 2025, accounting for 38.0% of the total market revenue. This dominance is fueled by the region's advanced digital infrastructure, widespread adoption of cloud-native platforms, and strong presence of leading technology vendors offering AI-driven observability solutions. The US market is projected to be valued at USD 0.5 billion in 2025, reaching USD 2.8 billion in 2034 at a CAGR of 20.0%. Europe holds a substantial share, with the market estimated to reach USD 400 million in 2025, driven by growing investments in cloud-native data infrastructure, widespread adoption of analytics and AI technologies, and a heightened focus on data compliance and governance due to regulations such as GDPR. The European market is expected to grow at a CAGR of 28.5% from 2025 to 2034. Asia Pacific is expected to witness the most significant growth in the global data observability market over the forecast period, driven by rapid digital transformation, growing cloud adoption, and the expansion of data-driven applications across emerging economies such as India, China, and Southeast Asian countries. Japan's market is projected to reach USD 80 million in 2025, reflecting its steady adoption of advanced data monitoring and reliability tools across key industries, with a forecasted CAGR of 24.7% from 2025 to 2034. Competitive Landscape The global competitive landscape of the data observability market is characterized by a mix of established technology giants and emerging startups, all striving to enhance their capabilities through innovation, strategic partnerships, and product differentiation. Leading players such as Datadog, Splunk, New Relic, and Dynatrace are leveraging their strong observability portfolios, while specialized vendors like Monte Carlo, Acceldata, Bigeye, and Anomalo focus on purpose-built platforms addressing data quality, pipeline monitoring, and real-time anomaly detection. Prominent players include Monte Carlo, Databand (IBM), Acceldata, Bigeye, Datafold, Anomalo, Soda, Metaplane, Collibra, Atlan, Alation, Splunk, Dynatrace, New Relic, Datadog, Cribl, Observe Inc., LogicMonitor, AppDynamics (Cisco), and Elastic N.V. Recent developments include Observe Inc.'s USD 156 million Series C funding (July 2025), DataBahn.ai's USD 17 million Series A funding (June 2025), Collibra's acquisition of Raito (June 2025), and Datadog's acquisition of Metaplane (April 2025). Technological Advancements Rapid advancements in AI, machine learning, and automation are transforming data observability platforms. AI-powered tools enable intelligent alerting, predictive analytics, and contextual root cause analysis, detecting anomalies in real time and reducing alert fatigue by filtering false positives. The integration of generative AI and natural language querying is also playing a significant role, simplifying data quality investigations and making observability accessible to business users and data stewards, not just engineers. Consumer Adoption Patterns Enterprises across BFSI, IT & telecom, healthcare, retail, government, and manufacturing are increasingly adopting data observability platforms to ensure data reliability, enhance governance, and support real-time decision-making. The growing availability of cloud-based and scalable observability solutions is making these tools more accessible to organizations of all sizes. Regulatory Environment Regulatory frameworks such as HIPAA, SOX, GDPR, and CCPA are pushing enterprises to adopt robust data observability platforms that ensure traceability, accuracy, and real-time alerting. Compliance with these regulations is a primary driver for observability adoption, as organizations must maintain data integrity and demonstrate auditability. Market Challenges The data observability market faces challenges related to high implementation costs, integration complexity, lack of standardization, and shortage of skilled professionals. Additionally, the evolving nature of the market and the absence of universally accepted metrics for data health can create confusion and hinder interoperability. Future Outlook The future of the Data Observability Market remains highly promising as data continues to be a strategic asset and organizations increasingly recognize the value of data reliability. Advancements in AI-powered observability, growing adoption of DataOps, expansion of cloud-native architectures, and increasing regulatory pressures are expected to drive strong market growth during the forecast period, with Asia Pacific emerging as a key growth region. FAQs What is the expected size of the Data Observability Market in 2025? The market is expected to reach USD 1.7 billion in 2025. What is the projected market value by 2034? The market is forecast to reach USD 9.7 billion by 2034. What is the CAGR of the Data Observability Market? The market is expected to grow at a CAGR of 21.3% during 2025–2034. Which component segment dominates the market? Software components are expected to dominate with approximately 72.0% share in 2025. Which region leads the global data observability market? North America is projected to lead with 38.0% of total market revenue in 2025. Summary of Key Insights The global Data Observability Market is expected to grow from USD 1.7 billion in 2025 to USD 9.7 billion by 2034, recording a CAGR of 21.3% during the forecast period. Software leads the component segment with 72.0% share, while cloud-based deployment dominates with 66.0% share. Structured data leads data types with 58.0% share, and large enterprises represent 68.0% of organization size share. Data pipeline monitoring leads applications with 28.0% share, and hospitals and clinics dominate industry verticals with 40.0% share. North America holds the largest regional share with 38.0% of global revenue in 2025, while Asia Pacific is projected as the fastest-growing region. The US market is projected to reach USD 2.8 billion by 2034 at a CAGR of 20.0%. Purchase the Full Report https://dimensionmarketresearch.com/checkout/data-observability-market/

Photo shared by James: Market Overview

According to Dimension Market Research, the Global Data Observability Market is p